
Spray Foam and Mortgage Problems
Spray foam can raise questions during a sale, purchase, remortgage or equity-release application. The right response depends on evidence, not pressure or assumptions.
Tell us what your lender, surveyor or adviser has requested. The free initial review is not a lender decision, valuation or structural survey.
Gather the evidence before deciding on work
Useful information can include clear loft photographs, installation paperwork, product details, warranties, reports and written lender, adviser, valuer or surveyor correspondence.
Requirements vary, so customers should confirm the evidence needed with the relevant lender, adviser or surveyor.
Start with the free remote photo review or use the checklist below to clarify what is being requested.
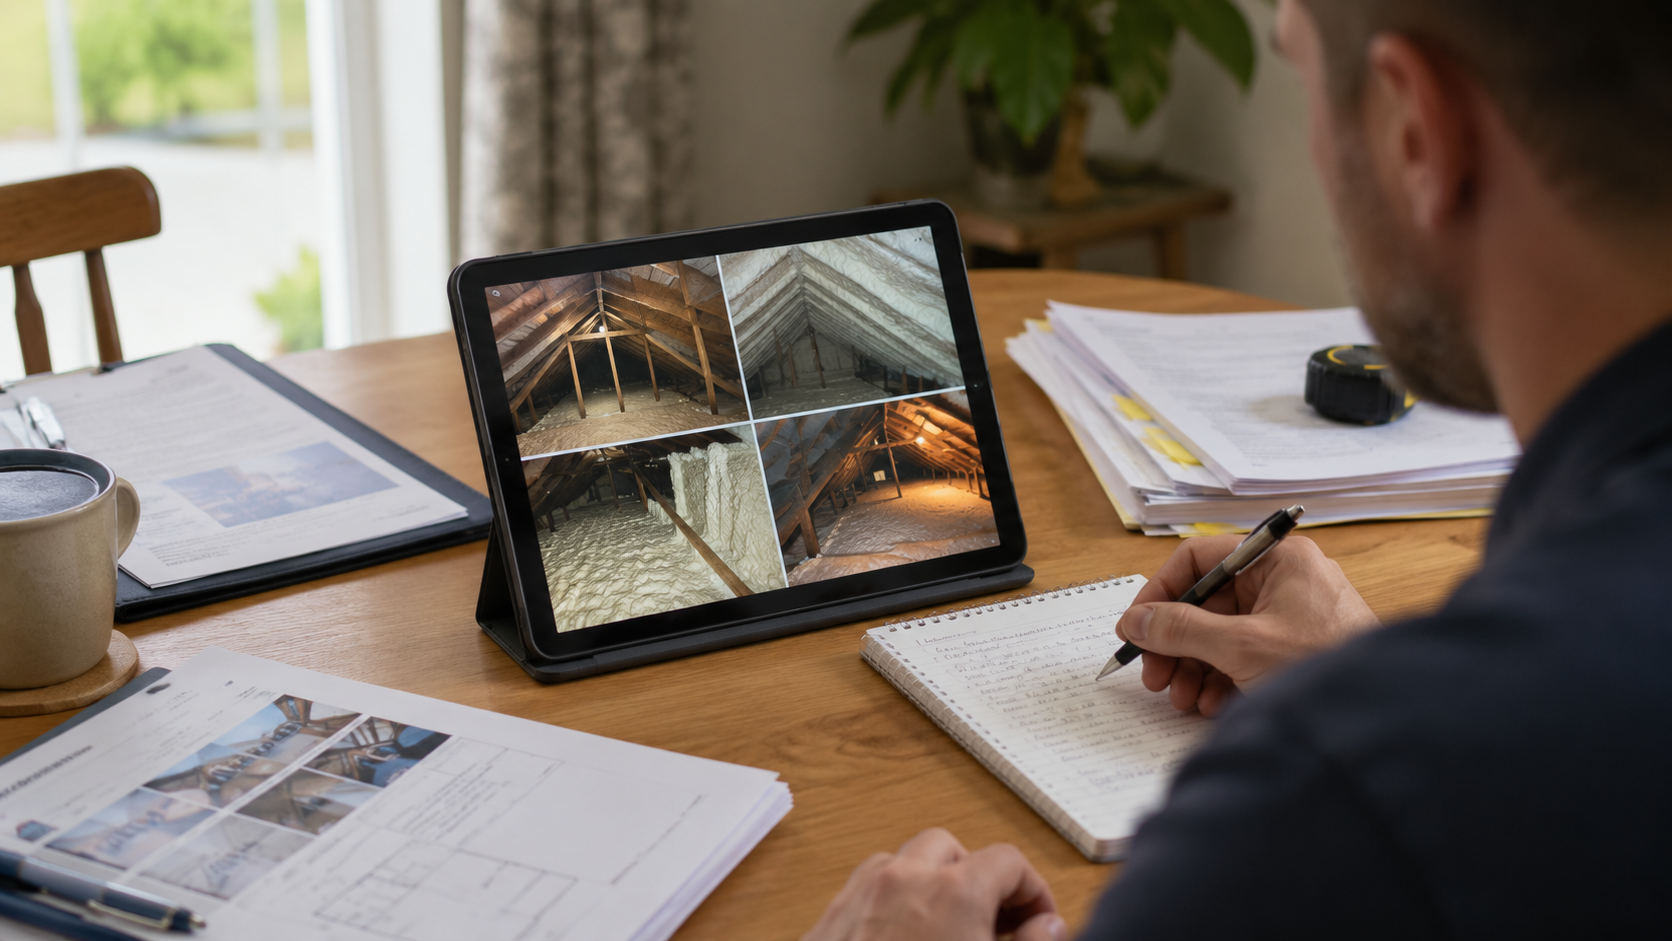
Why lenders and surveyors ask questions
Foam may conceal parts of the roof structure and can make timber, felt, membranes, ventilation paths and moisture condition harder to see.
Paperwork helps but is not decisive
Installation certificates, product data, warranties and photographs can be useful, but incomplete records can make assessment harder.
Removal is not an automatic answer
Removal should not be recommended without understanding foam type, roof construction, accessible timber condition and the customer's objective.
Next sensible step
A review may lead to additional evidence, on-site assessment, specialist advice, targeted remediation, removal or no immediate work.
Questions to ask your lender, broker, adviser or surveyor
- What specific information or evidence is currently missing?
- Is removal definitely required?
- Would a further inspection or specialist report be considered first?
- Does the foam type affect the requirement?
- Is complete removal required or only work in specified areas?
- Is independent surveyor, roofing or structural input required?
- What evidence would allow the property to be reconsidered?
- Who will make the final lending or valuation decision?
- Are there any format or wording requirements for completion evidence?
This is preparation guidance only, not legal or financial advice.
Request a Free Remote Photo Review
Start with photographs and background information. If the issue cannot be assessed remotely, Insofix will explain whether a chargeable on-site assessment is the sensible next step.